UAE Domestic Minimum Top-up Tax
GloBE income, ETR, 15% floor, substance carve-outs, de minimis, verified
UAE DMTT for Fiscal Years from 2025: scope test, Pillar Two Income, covered taxes, ETR, 15% floor, SBIE at transition rates, de minimis, safe harbour, deadline.
Choose the licence on the Gumroad page. Payment and VAT are handled by Gumroad, the merchant of record.
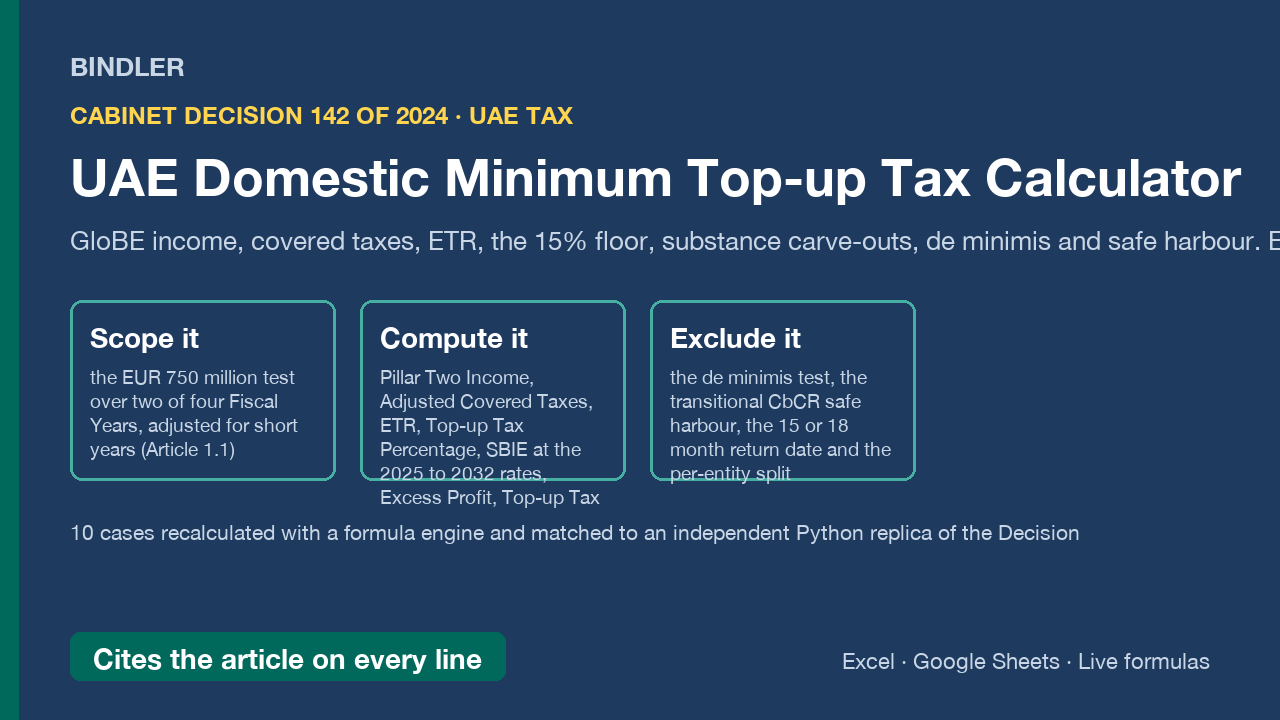
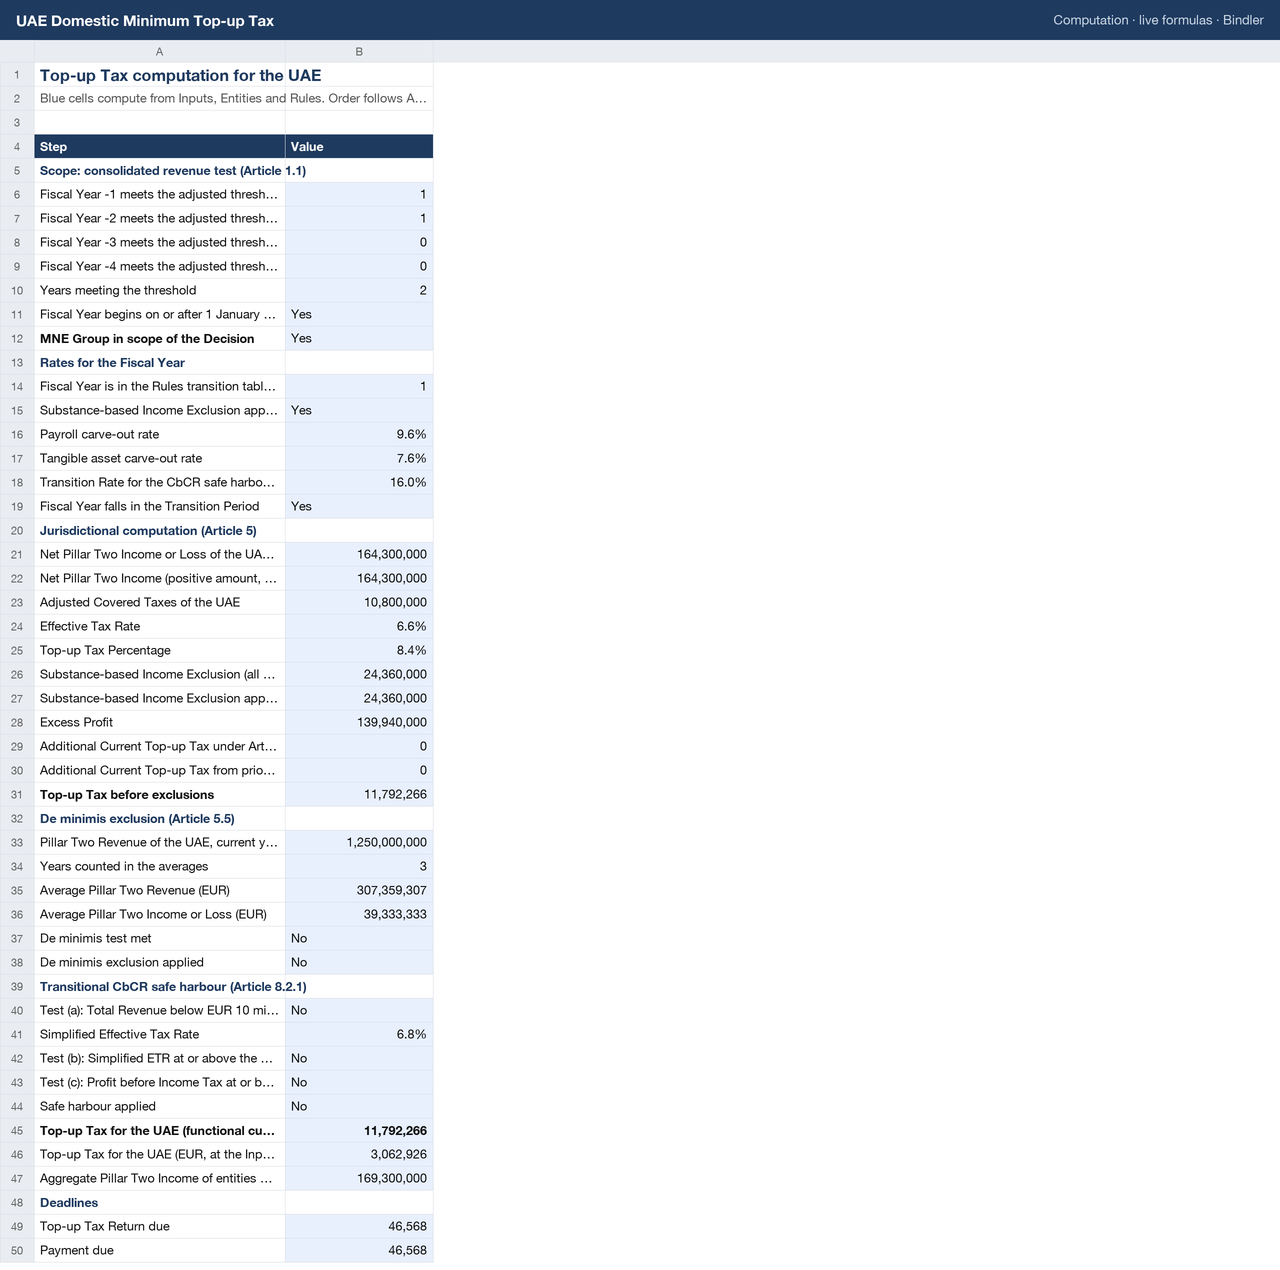
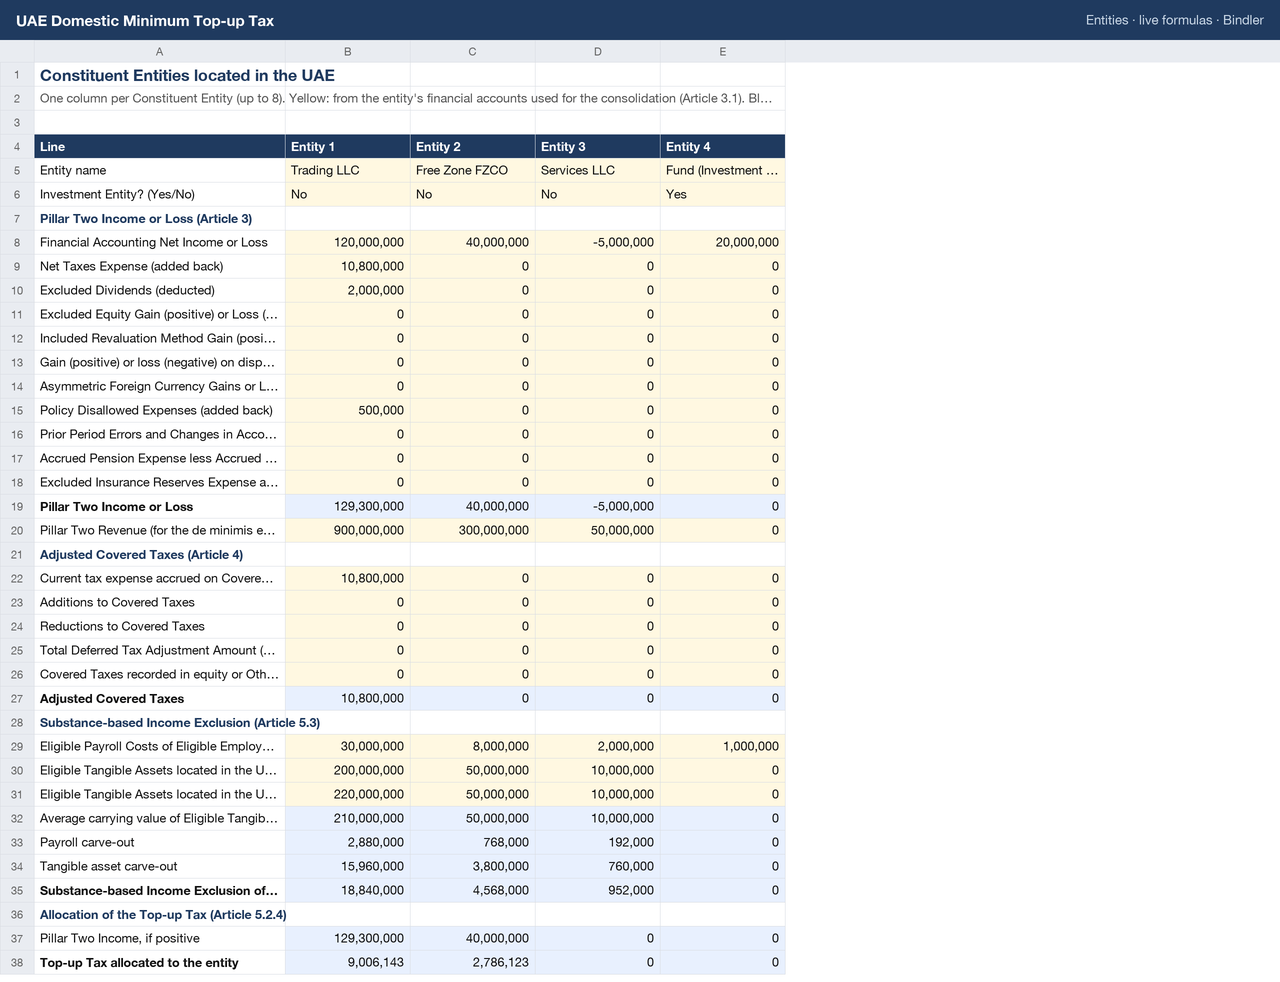
Cabinet Decision No. 142 of 2024 imposes a Domestic Minimum Top-up Tax on UAE Constituent Entities of MNE Groups with consolidated revenue of EUR 750 million or more in at least two of the four preceding Fiscal Years (Annexure Article 1.1.1), for Fiscal Years beginning on or after 1 January 2025 (Article 2 of the Decision). This workbook runs the Decision's own arithmetic for the UAE as one jurisdiction: the revenue test with the Article 1.1.2 short-year adjustment, Pillar Two Income or Loss per entity from Financial Accounting Net Income and the Article 3.2.1 adjustments, Adjusted Covered Taxes (Article 4.1), the Effective Tax Rate and Top-up Tax Percentage against the 15% Minimum Rate (Articles 5.1 and 5.2), the Substance-based Income Exclusion at the Article 9.2 transition rates (9.6% payroll and 7.6% tangible assets for 2025, stepping down to 5.8% and 5.4% for 2032), Excess Profit and the Top-up Tax (Article 5.2.3), the Article 4.1.5 additional tax when covered taxes turn negative, and the split between entities under Article 5.2.4.
Two exclusions can set the result to zero and both are tested: the de minimis exclusion (Article 5.5: Average Pillar Two Revenue below EUR 10 million and Average Pillar Two Income below EUR 1 million over the current and two preceding years) and the Transitional CbCR Safe Harbour (Article 8.2.1: the EUR 10 million and EUR 1 million test, the Simplified ETR against the 16% or 17% Transition Rate, or the routine profits test) for Fiscal Years in the Transition Period. The return and payment dates follow Articles 8.1.2 and 11.1: 15 months after the Fiscal Year end, 18 in the first Transition Year, paid in UAE Dirhams.
- Every threshold, rate and date sits on a Rules sheet with its article; the Sources sheet links the Decision as published by the Federal Tax Authority and the Ministry of Finance Top-up Tax page.
- Ten cases (in and out of scope, 2025 and 2026 rates, a short year, de minimis, safe harbour, Article 4.1.5, SBIE waived, ETR above 15%, a 2033 year at the standard 5% rates) were recalculated with a formula engine and matched to an independent Python replica before listing.
- Up to eight UAE Constituent Entities, Investment Entities excluded as Articles 2.3 and 5.1.3 require. Live formulas, no macros, no locked cells; opens in Excel and Google Sheets. A working tool, not tax advice: the entity classification, Covered Taxes and the elections are facts you confirm, and the Guide says where.
Checked, not asserted. This workbook was recalculated cell by cell through a formula engine and matched against an independent replica written separately: 10 checks, all passing, last run 2026-10-17. Each check compares the figure the workbook produces against one worked out separately by hand before the run, so a figure lost in packaging fails the check rather than reaching you. Read the verification report for the UAE Corporate Tax workbook, or how Bindler verifies.
What was checked: all 10, by name
Each line is one figure recalculated and matched against a value worked out by hand before the run. The figures themselves are in the workbook.
- A base : ETR below 15%, SBIE at %/%, tax allocated to the two profitable entities
- B out of scope: only one of four years at EUR
- C rates %/%, Transition Rate 17%, return 15 months
- D de minimis elected and met: small UAE footprint
- E safe harbour elected: Simplified ETR % at or above 16%
- F Article .5: net Pillar Two Loss, negative Adjusted Covered Taxes
- G SBIE not applied: full Net Pillar Two Income is Excess Profit
- H short Fiscal Year -1 of 6 months: EUR adjusted threshold met
- I : standard 5% rates, no Transition Period, no Transition Rate
- J ETR above 15% (20/): Top-up Tax Percentage zero
What is inside
1 Excel workbook (.xlsx), sheets: Inputs, Computation, Entities (up to 8), Rules, Guide, Sources.
Use it if
You prepare, review or audit the Top-up Tax position of UAE entities in a group at or near EUR 750 million consolidated revenue and need a defensible first computation before the return is due.
Not for
You need the full OECD GloBE model across several jurisdictions, deferred tax recasting or the Article 7 special regimes; this workbook computes the UAE jurisdiction under the Decision and structures the inputs you enter.
Who you are buying from
Bindler is the trading name of Neil Sangwaiya, one person in Dubai. There is no company behind that name, no sales team and no reviews, and this page is not going to pretend otherwise. What there is instead is a record. Gumroad takes the payment and is the merchant of record, so your card details never reach Bindler. Where a figure could not be verified the cell is left blank rather than filled. When something was found wrong it was written down and dated in the change log with the old figure named. And there is a 30-day money back guarantee, no reason needed, handled by Gumroad.
What you actually download
One spreadsheet file. No macros and no VBA, because the .xlsx format cannot carry them. No locked cells and no hidden sheets. If your IT will not let you open a spreadsheet from outside, upload it to Google Sheets and it opens there. And yes, an AI built it: that is exactly why every figure is recalculated against a replica worked out by hand first, rather than trusted.
Sheet previews
How buying works
- Choose a licenceSingle user for one person, team for up to 10, consultancy to use with clients. The buttons above go to the Gumroad page.
- Pay on GumroadCard or PayPal; Gumroad is the merchant of record and handles VAT and the receipt.
- Download the fileThe .xlsx arrives on the receipt page and by email. It opens in Excel and Google Sheets; nothing to install.
- Use itYellow cells are inputs, blue cells are formulas, every figure names its source. Questions: reply to the receipt; every reply is read and answered, usually the same day.
Advisers and accountants who recommend these workbooks to clients can earn 30% of each sale as a Gumroad affiliate: sign up on the store, no approval wait.
Search terms this page answers: uae domestic minimum top-up tax calculator, uae dmtt excel, cabinet decision 142 of 2024, pillar two uae, globe effective tax rate calculator, substance based income exclusion.